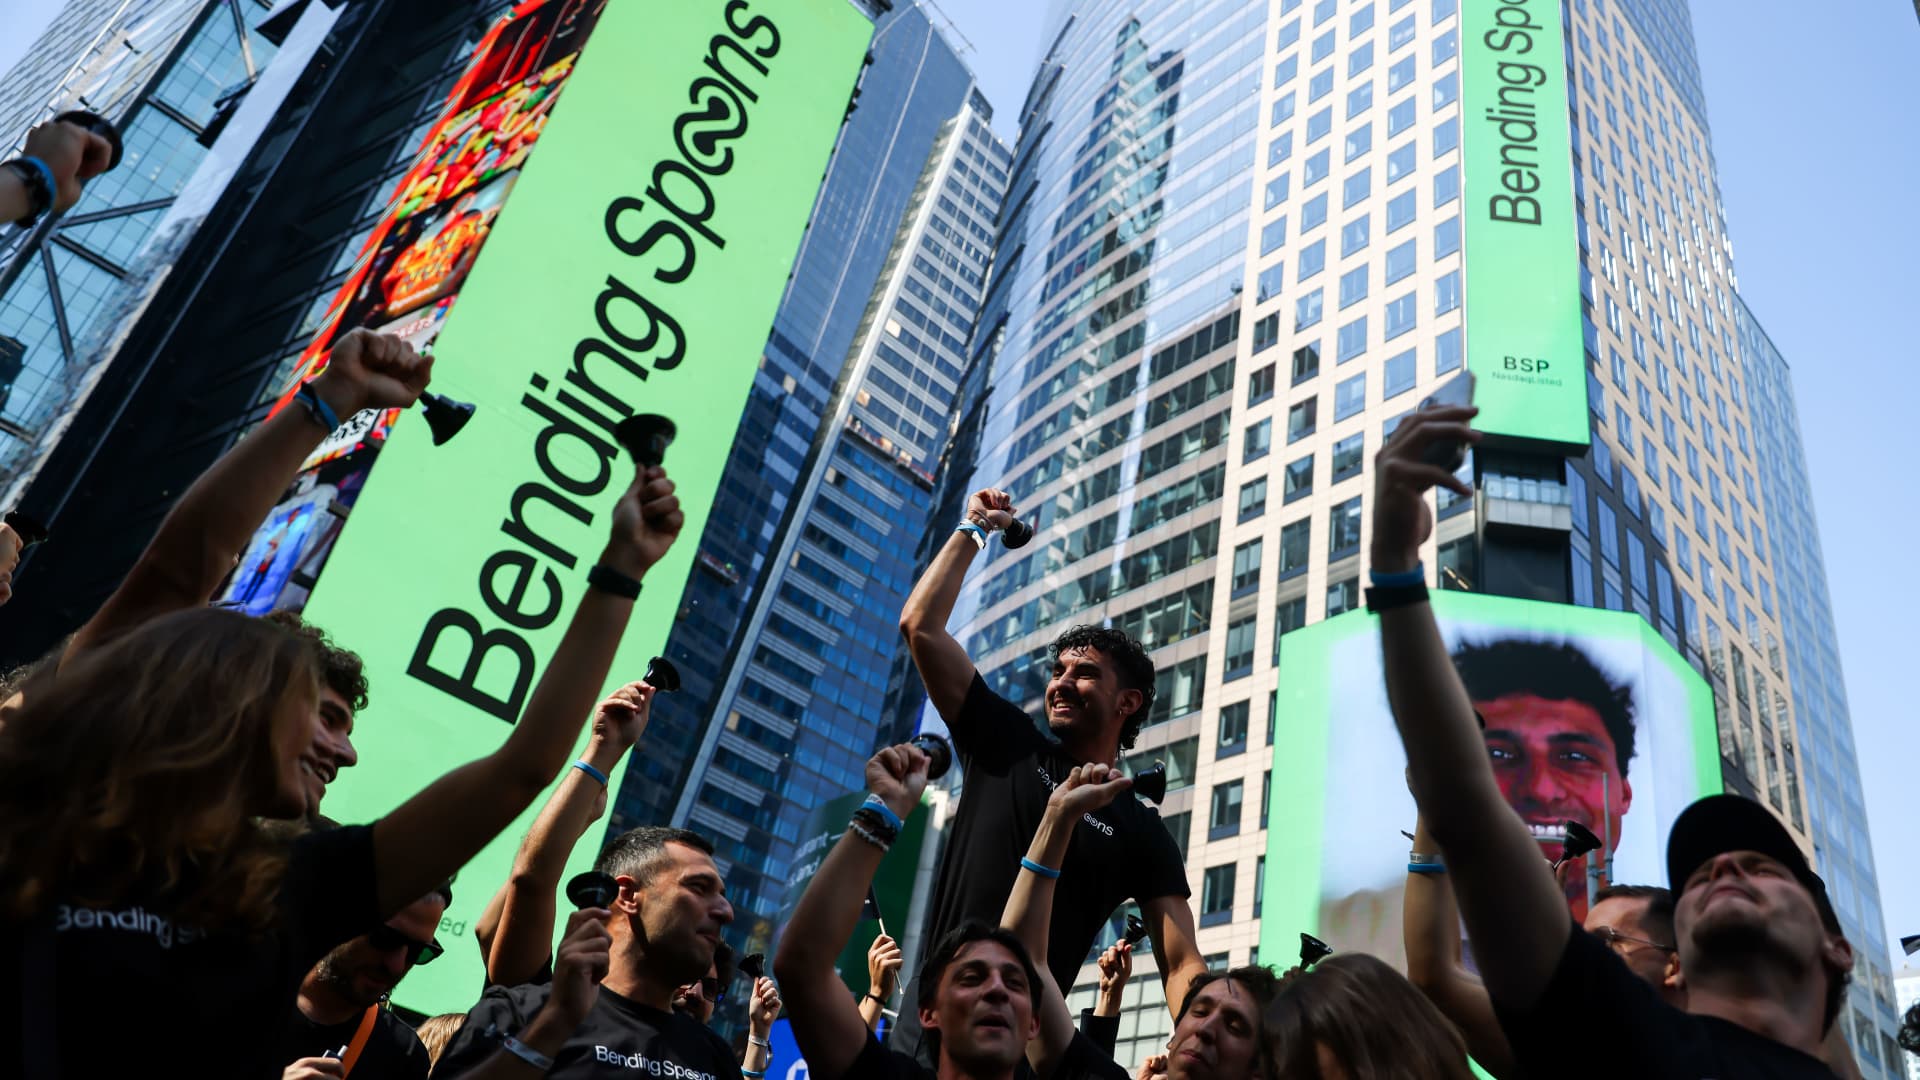
Guests during the Bending Spoons initial public offering (IPO) on the Nasdaq MarketSite in New York, USA, on Wednesday, July 1, 2026. Michael Nagle | Bloomberg | Getty Images At the time of its Nasdaq debut in July, Bending Spoons was a little-known holding company from Italy that owned older Internet names like AOL, Vimeo, Eventbrite and Evernote. Less than four months later, the Milan-based company has become a surprising home for former high-flying software startups that have been sidelined by the rise of artificial intelligence. Its mergers and acquisitions plan received a big boost this week from the most famous holding company on the planet: Berkshire Hathaway. Berkshire, which Bending Spoons describes as a “long-standing inspiration” for its strategy, has invested more than $900 million in the company, including a $330 million stake disclosed Wednesday. Wall Street loved the deal, sending Bending Spoons shares up 41%, although some of those gains were lost later that week, leaving the company with a market capitalization of around $30 billion. “Berkshire’s decision to increase its position just months after the IPO and at these levels provides another vote of confidence in the Bending Spoons model from one of the world’s most respected long-term investors,” analysts at Mizuho wrote, in a report after the announcement. The other big news from Bending Spoons this week underscores the other side of the business: job cuts. In August, Bending Spoons announced it would buy workflow software provider Airtable for about $1.3 billion, or nearly 90% below the company’s highest valuation since the end of 2021. Bending Spoons said Monday that a “large portion of Airtable’s pre-acquisition team” would leave in “substantial separation packages.” Layoffs were previously implemented at Evernote, Vimeo, WeTransfer and others in the portfolio. For the tech industry, Bending Spoons’ moves represent the latest example of how quickly fortunes are changing in the age of AI, as new agents powered by large language models displace software developers and the products they built. With Anthropic and OpenAI advancing toward trillion-dollar valuations, companies are putting more valuable work in their hands at the expense of a host of software-as-a-service names, creating a phenomenon known as the “SaaSpocalypse.” Shares of Intuit, HubSpot and Adobe have fallen at least 30% this year, and a long list of private SaaS companies that were once darlings of venture firms are now struggling to find capital, with the public market showing no appetite for IPOs. Last month, Bending Spoons agreed to buy collaboration software provider Miro, once valued at $17.5 billion, for $1.36 billion. “You’re either something sexy or you’re nothing,” said Ethan Kurzweil, founder and managing partner of Chemistry VC and a veteran software investor. Kurzweil said he uses Airtable and said there are a lot of good SaaS products on the market led by strong teams, “but they’re not on the frontier anymore.” In 2013, friends Luca Ferrari, CEO Matteo Danieli and Francesco Patarnello launched app-turned-acquirer Bending Spoons. A mobile app they had created called Evertale failed to take off, and they used their remaining $40,000 to build an operating company instead of “products no one wanted,” according to the IPO prospectus. Bending Spoons has announced all of its biggest deals in recent years, starting with Evernote in 2022, followed by Brightcove in 2024, and Vimeo, AOL, and Eventbrite in 2025. The company held its initial public offering (IPO) on June 30, raising about $1.7 billion at $29 per share, and hit the Nasdaq the next day. The stock closed Friday at $47.07. Stock Chart Icon Stock Chart Icon Bending Spoons stock chart since its July 1 IPO date. Before Bending Spoons’ recent jump into enterprise software, some of the biggest acquirers in the space over the past decade were private equity giants Thoma Bravo and Vista Equity Partners. Those companies aimed to buy what they considered undervalued SaaS companies and, through a combination of cost cuts, efficiency improvements and accruals, turn them into assets that could be sold or taken public at a higher price. Bending Spoons is using a different playbook. The company does not look for possible exits but rather wants to generate profits from the businesses it buys, similar to Warren Buffett’s model. But unlike Berkshire, Bending Spoons’ focus is on technology and it is taking a hands-on approach with its own software, operations and personnel decisions. Nick Mehta, former CEO of cloud software provider Gainsight, said private equity firms are limited now because they “got a bloody nose.” “They paid much higher prices and they have so many companies in trouble that it’s hard for them to make changes now,” said Mehta, who sold Gainsight to Vista in 2020. Thoma Bravo and Vista did not respond to interview requests. Bending Spoons told CNBC in a statement that they had not been outbid for a target in “several years.” When the company began to launch into SaaS, Mehta said “Bending Spooned” became a verb in Silicon Valley, referring to companies that were bought for pennies on the dollar. “Unfortunately, a lot of my friends in that game are stuck,” Mehta said. “Investors want out but there are no buyers. Everything before ChatGPT is now a legacy.” Lloyd Walmsley, an analyst at Mizuho, said Bending Spoons’ model is different from the old purchasing approach. “I don’t think there are many people who do what these guys do in terms of depth of operations and willingness to make substantial changes to products,” Walmsley said in an interview. “It’s not typical for traditional private equity firms to achieve anywhere near this level of change.” Bending Spoons co-founder Matteo Danieli, center, during the company’s initial public offering (IPO) on the Nasdaq MarketSite in New York, U.S., Wednesday, July 1, 2026. Michael Nagle | Bloomberg | Getty ImagesFor customers of companies that Bending Spoons purchases, sudden price increases may occur. In April 2023, months after acquiring Evernote, Bending Spoons raised the price of the annual personal subscription from $70 to $130. The company later changed its offering, charging $100 for its so-called starter plan and $250 for “Evernote Advanced,” compared to the $170 it had been charging for the professional plan. “My first reaction was like, Oh man, I guess I have to switch to OneNote,” Walmsley said, referring to Microsoft’s note-taking app. But he said he stuck with Evernote. “They’re very adept at finding these things that add a lot of value, and the switching costs are really high,” Walmsley said. “The price is not that high relative to the switching cost.” Bending Spoons uses profits from its portfolio companies for future growth, the “overwhelming majority” of which comes from closing more deals, Ferrari told CNBC in an interview Thursday. “There are certain opportunities for improvement that we can unlock during the first few years, and then the business will have the organic growth that is intrinsic in that market,” Ferrari said. For Berkshire and his fellow Bending Spoons investors, the bet is still unproven. Products must remain attractive enough that customers are willing to pay at a time when AI is reducing margins in much of the software sector. In its first earnings report as a public company in August, Bending Spoons said revenue doubled from a year earlier to more than $700 million, with growth driven almost entirely by acquisitions, while net income rose 171% to $177 million. That was before the Airtable deal was closed and Miro had not yet been announced. In the coming quarters and years, Wall Street will have a clear idea of whether the company’s structure can revive the software. On the August earnings call, an analyst asked whether Airtable represents a long-term shift in M&A strategy toward the company. Ferrari said about half of Bending Spoons’ revenue already comes from professional businesses, largely through Brightcove and Vimeo, which has an enterprise component. The focus on software lately, he said, has more to do with where it is finding value after a sharp sell-off. “Most enterprise SaaS businesses were valued at unreasonably high levels until recently,” Ferrari said. “We never saw those prices making sense.” CNBC’s Ari Levy contributed to this report.